
Is AI a Bubble? Ask the Tulip Monkeys
Is AI a Bubble? Ask the Tulip Monkeys
By TechPulse USA
San Francisco, October 17, 2026
Everyone keeps asking whether artificial intelligence is a bubble. This week the International Monetary Fund warned of a dot-com-style correction, Ray Dalio told a Singapore audience the boom is near its breaking point, and a London strategist put a date on the pop — 2027 or 2028 — while Anthropic kept posting revenue numbers that look like a growth fantasy. So here is the honest answer: both camps are half right. The technology is genuinely transformative, and the financing looks genuinely unhinged. The interesting question was never whether there is froth. It is whether the froth matters.
We spent this week reading the actual research — the Cornell paper, the Bank of America fund-manager survey, the IMF's October stability report — instead of the shouting. What follows is the strongest version of each case, with no strawmen, and then our verdict, including the evidence that would change it.
The monkey painting from 1640 has seen this before
Start with the painting at the top of this article. In about 1640, Jan Brueghel the Younger painted Dutch speculators as monkeys — monkeys weighing bulbs, monkeys counting money, one monkey urinating on tulips whose purchase deeds had just become worthless. The Dutch tulip market had collapsed in February 1637, ruining investors who had paid canal-house money for flower bulbs. Nearly four centuries later, the painting still shows up on the Wikipedia page for "economic bubble," because every generation thinks its speculation is the first and last of its kind.
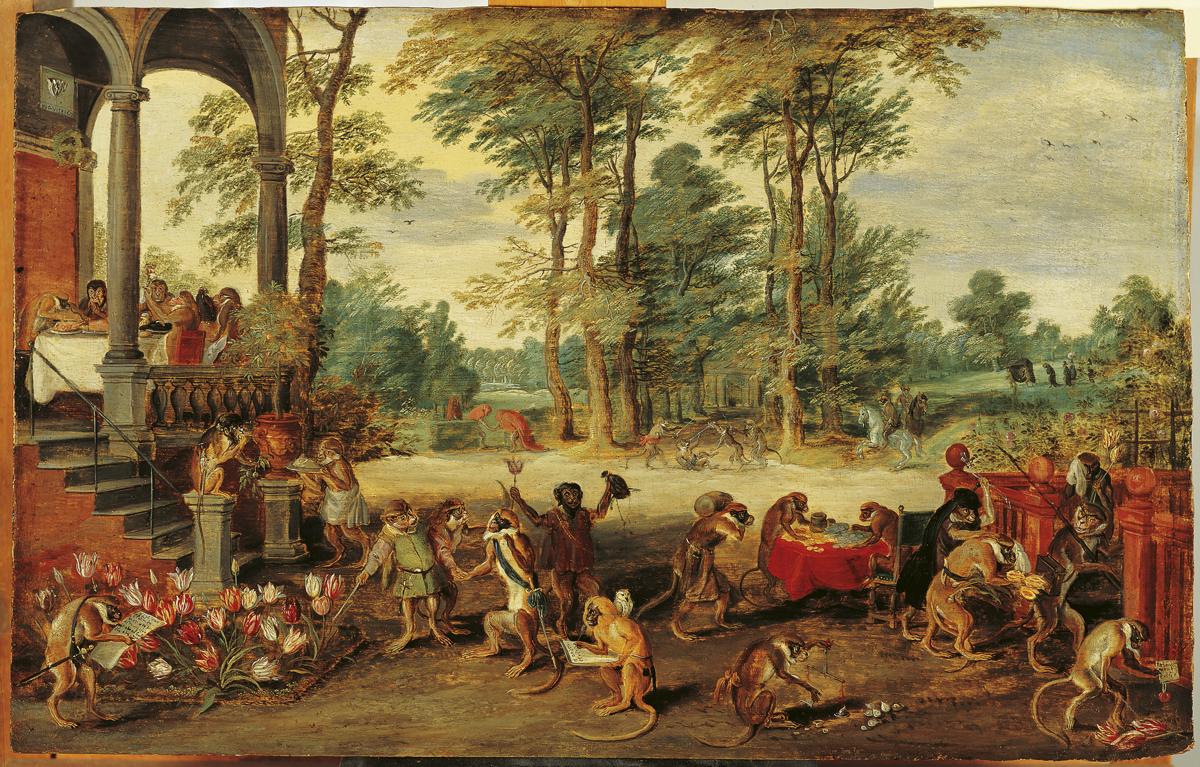
Photo: Jan Brueghel the Younger, "Satire on Tulip Mania" (c. 1640), oil on panel. Brueghel painted the Dutch speculators as foolish monkeys — weighing bulbs, counting money, one urinating on now-worthless tulips. Credit: Frans Hals Museum / Wikimedia Commons (Public Domain).
Every bubble has its monkeys. The railways of the 1840s, rural electrification, the fiber-optic buildout of the 1990s, the dot-com crash of 2000 — each was a genuine infrastructure revolution financed by people who paid too much, too fast. Paul Kedrosky, the economist and investor, put it this way in an interview with Derek Thompson this year: "AI is a bubble because it's one of the probably five largest CapEx bubbles in history." His point was not that AI is useless. His point was that AI is a canal, a railroad, a power grid — and those things have always been overbuilt first and repriced later, in what he calls "rotating crashes" where the assets survive and the investors don't.
The dot-com parallel is the one everyone reaches for, and it is worth getting right. The Nasdaq fell nearly 78% between March 2000 and 2002. But the internet did not die; it needed a decade for viable business models to emerge. Amazon, founded in 1994 and listed in 1997, took roughly nine years to post a full-year profit, spending most of that time building warehouses and teaching consumers to trust online payments. AI today looks a lot like that second phase: real demand, real utility, funded by the richest balance sheets on Earth rather than by junk bonds. That difference matters more than the headlines admit.
The bull case: this time the revenue is actually real
The strongest argument against the bubble case is also the simplest: the money coming in is no longer hypothetical. Anthropic's second quarter of 2026 is the proof point the bears have to deal with. According to investor materials reported by the Wall Street Journal and Reuters, Anthropic posted roughly $10.9 billion in revenue in the quarter — more than double the $4.8 billion it made in Q1 — and turned its first-ever adjusted operating profit of $559 million. A year ago the company kept about 38 cents of every revenue dollar after paying for compute; by mid-2026 it was keeping about 70 cents, as cheaper inference, custom silicon and better model efficiency slashed the cost of serving each query. Revenue more than doubled while compute efficiency roughly doubled too. That is not a PowerPoint metric. That is a business.

Photo: Server racks at the NERSC supercomputing center — the kind of compute infrastructure the AI industry is racing to build, at a pace Goldman Sachs estimates at $600–750 billion of global AI capex this year. Credit: Wikimedia Commons (CC0).
The scale is what startles. By May 2026, Anthropic's annualized revenue run rate had crossed $45–47 billion, briefly passing OpenAI's roughly $40 billion, per reporting from The Information cited by Sherwood News. OpenAI, meanwhile, had its annualized run rate at about $50 billion at the end of September and is aiming past $70 billion by year-end, according to Bloomberg — with the Financial Times reporting the company expects that growth to cost it $278 billion in cumulative negative free cash flow between 2026 and 2030. We cross-checked the Q2 figures across five outlets — Reuters, the Journal, The Information, Bloomberg and Sacra — and the $559 million operating-profit number holds up in every telling, including Anthropic's own warning to investors that later quarters may not stay profitable as compute costs ramp. A company that achieved an adjusted operating profit and then immediately warned it might not last is many things; a fraud is not one of them. The trajectory is what you would expect from a technology crossing into the mainstream, not from a tulip bulb. (We covered Anthropic's first profitable quarter — which Wall Street sold off anyway in detail this week.)
There is a second, quieter bull argument, and it comes from Lombard Odier's global chief investment officer Michael Strobaek, who told reporters this month that investors should not be "too afraid" the AI bubble is about to burst, that it is far too early to call one, and that short-sellers betting against the boom could get very badly burned. He has history on his side: the people who called the internet bubble too early in 1996 and 1997 paid dearly for it. Bubbles can be real and still take years to arrive — and profitable.
The bear case: money moving in circles
Now the case that keeps me up at night. It is not that AI companies sell nothing — it is that some of what they count as demand is money they put into the market themselves. The IoT Analytics team, which published a fresh analysis this week, lists five reasons the data-center buildout may not pay for itself: enterprises still can't show material revenue gains or fast payback periods from their AI investments; hyperscalers, labs, chip vendors and financiers increasingly fund one another, and that capital is spent back on cloud and GPU capacity; every cloud giant is rationally hoarding compute, which in aggregate risks building more capacity than the market needs; GPUs become economically obsolete before they earn their cost back; and efficient open-weight models are shifting routine inference off rented infrastructure onto commodity hardware.
The circularity is the centerpiece. OpenAI generated about $12.6 billion in 2025 revenue — and carries more than $550 billion in cloud commitments. Nvidia's vendor guarantees to customers are capped at around $105 billion, roughly 35% of its last twelve months of revenue; the last company to finance its customers' purchases on this scale was Lucent, and that ended exactly how you remember. The Financial Times' figure — $278 billion of negative free cash flow projected for OpenAI through 2030 — tells you the labs know the gap too.
This is why the grown-ups are nervous. The IMF's October Global Financial Stability Report names "circular financing arrangements, in which AI firms act as one another's investors, financiers, and customers" as a specific systemic risk: trouble at one company becomes somebody else's problem instantly. Gary Marcus, the NYU professor and longtime AI skeptic, called AI infrastructure spending "the greatest capital misallocation in history" in June — bombast, but aimed at a real number. And Joachim Klement, the Panmure Liberum head of market strategy who has gone the most bearish, is unusually precise: "My core conviction is that the AI bubble will either burst in 2027 or in 2028, so sometime in the next two years." Note the texture: as recently as mid-September, Klement's assumption was that the S&P 500 would hit 8,300 by the end of next year. Now his 2027 target is 5,000 — implying 36% downside — because hyperscalers' free cash flow is depleting while the cost of debt rises. A strategist flipping that hard, that fast, is either panicking or early.
The fund managers, collectively, cannot decide. Bank of America's October survey of 161 managers overseeing $453 billion found 45% expecting an AI bubble in 2027 and 42% disagreeing — while a net 37% kept increasing their overweight to tech and cash fell to 3.9%, below the bank's contrarian sell-signal threshold. That is the whole argument in one paragraph: the people closest to the money think the trade might be a bubble, and they are buying it anyway. (We've tracked the money flows separately: the $113 billion debt machine behind the AI buildout, Wall Street's biggest-ever bet on AI infrastructure, and Michael Burry's puts, which bet the bubble bursts in 2027.)
What would actually pop it — and what would validate it
Dates from bears are always a guess, but the mechanism is worth spelling out. Watch enterprise behavior, not stock prices. The moment large customers start switching to cheaper models to cut their AI bills — which, according to industry analysis this week, began in mid-2026 — the "pay anything forever" assumption is already breaking. A pop looks like this: a financing event (a failed bond sale, a credit downgrade, a big customer defaulting on a lease commitment) triggers a re-rating of the whole circular chain, and because the ten biggest S&P 500 names hold nearly 38% of the index, the selloff lands in everyone's pension. AI-related investment was already near 5% of US GDP by early 2026, per one macro estimate — big enough that a bust would not stay in Silicon Valley.
Validation looks like the opposite: enterprise ROI studies that actually show payback, Anthropic-style margins spreading to other labs, and capex converting into free cash flow. There is a live version of this debate at the top of the industry. In London this week, Nvidia's Jensen Huang — standing on a pop-up stage in an old converted church in West London, per The Tech Download's newsletter — dismissed bubble fears and used the trip to warn Britain against relying on "opaque" models from the big American labs for mission-critical work: "How could you have an opaque agentic system, be contained in an opaque box, run by an opaque company? It's obviously not sustainable." You can read that as the shovel-seller talking his book — Nvidia sells the hardware under all of this — but a self-interested argument is not automatically a wrong one. Cornell's statistical analysis lands in the middle: Martin Wells and Abir Sarkar concluded that "some segments of AI-related companies exhibit characteristics consistent with speculative bubble dynamics, while others do not" — with Alphabet, up more than 70% in a year, showing strong evidence of overvaluation. Treating "AI" as one thing, Wells says, obscures what is actually happening.
Our verdict: yes, it is a bubble — in the money, not the machines
Here is where we stop hedging. Yes, parts of this are a bubble. The financing structures are bubble-like: the circular deals, the lease commitments dwarfing revenues, the fund managers buying what they privately suspect is overheated. Valuations in parts of the market are bubble-like: Alphabet at those multiples, startups raising billions on vibes, OpenAI worth $852 billion while projecting $14 billion in annual losses. But the technology is not a bubble. AI is the internet of 1999, not Pets.com of 1999 — a general-purpose technology being financed like a mania, which is exactly how railroads, electricity and fiber got built too. If the pop comes, it reprices expectations and wipes out investors, not the technology. Most AI companies should die; that is the system working, not failing.
What would change my mind? Two things. First, audited enterprise ROI data showing that AI spend pays for itself at scale — if that never arrives, the bear case wins outright. Second, the utilization data: if the data centers now being financed at $600–750 billion a year end up half-empty in 2028, Klement's 2027 target starts looking optimistic. Until then, the honest position is uncomfortable: stay exposed to the technology, stay skeptical of the financing. The monkeys in the painting were not wrong to trade tulips. They were wrong to pay canal-house prices for them. (Related: OpenAI's $50 billion revenue gap and why Broadcom's Hock Tan says AI's biggest problem isn't chips, it's capital.)
Is AI a bubble? Your questions, answered honestly
Is AI a bubble right now?
Most likely, there is a real bubble in parts of it — yes. The spending (roughly $600–750 billion of global AI capex this year, per Goldman Sachs estimates) wildly outruns the revenue anyone can count (under $100 billion a year industry-wide). But it is not a clean repeat of 2000: today's leaders are hugely profitable businesses funding the buildout from cash flow, not loss-making startups funded by junk debt. The honest read is high probability of froth, not a guaranteed crash — exactly where Cornell's researchers landed.
Will the AI bubble burst — and when?
Nobody can give you a date honestly; anyone who does is guessing. Joachim Klement says 2027 or 2028; Ray Dalio says the boom is near its breaking point; Bank of America's fund-manager survey splits 45/42 on whether a bubble even arrives next year. What history says is clearer: when spending races this far ahead of real demand, a correction of some kind usually follows. The tell to watch is not the stock price — it is enterprise behavior. If big customers keep switching to cheaper models to cut AI bills, the "pay anything forever" assumption is already breaking.
Are AI companies actually making money?
It depends which AI company. The infrastructure providers are enormously profitable — Nvidia is the most valuable company in history. The model labs are a mixed picture: Anthropic posted its first adjusted operating profit of $559 million in Q2 2026 on roughly $10.9 billion of revenue, with inference margins that have roughly doubled in a year. OpenAI, despite revenue approaching a $70 billion annualized run rate, projects $14 billion in losses for 2026 and $278 billion in cumulative negative free cash flow through 2030. Revenue is real; profits are a frontier-lab problem, not an industry problem.
Why is AI making my laptop and phone more expensive?
Because AI data centers and your gadgets compete for the same memory chips, and AI buyers pay far more per chip — so factories shifted production toward them and created a shortage for everyone else. One industry analysis this week notes memory prices have risen sharply enough that even Apple raised prices mid-year and openly blamed the AI-driven component surge. You are, in effect, paying an AI tax at the checkout. It is one of the few bubble costs ordinary people feel directly, whatever happens to the stocks.
What happens if the AI bubble pops?
The IMF's warning this month is the one to take seriously: with tech giants borrowing billions, valuations stretched and financing circular, a selloff could extend well beyond technology — the top ten S&P 500 names hold nearly 38% of the index, so your pension feels it too. But the dot-com lesson cuts both ways: in 2000–2002 the Nasdaq lost 78% and the internet survived, emerging stronger. A pop reprices expectations and wipes out investors; it does not uninvent the technology. The assets — the data centers, the fiber, the models — get bought cheap and find new uses. That is what happened with every canal, railroad and fiber network before this one.
Sources: Reuters, The Wall Street Journal, The Information (via Sherwood News), Bloomberg, Financial Times (via Sacra), Axios, IMF October 2026 Global Financial Stability Report, Bank of America October fund-manager survey, Cornell University / Frontiers in Mathematical Finance, The Times (London), The Hindu BusinessLine, Tech Xplore, IoT Analytics, Derek Thompson's interview with Paul Kedrosky, The Tech Download.
TechPulse USA is an independent tech news publication covering artificial intelligence, chips and markets. We read the filings, the research and the footnotes — so you don't have to.
Update, Oct. 17
Anthropic's Q3 revenue hit $16.8 billion — up 45% quarter over quarter — at its October 14 investor day, but growth decelerated from the +147% Q1-to-Q2 jump, and some investors began pricing the November IPO at around $1.5 trillion instead of the $2 trillion target (Reuters, October 15, four people familiar). A record quarter and a second straight adjusted-profit quarter — alongside a $500 billion repricing in the same 24 hours. This pillar's verdict in miniature. (We covered it here: Anthropic's 45% Growth Wasn't Enough for the $2 Trillion IPO.)
Anthropic also cut model-distillation revenue (5–7% of revenue) "materially" in Q3, the Financial Times reported — a moat-protection move that will weigh on Q4 growth. The IPO marketing week is reported for November 9 (Bloomberg); we'll refresh this note when pricing lands.


Comments
Post a Comment